
On this page 6 sections
If money has left your account through a UPI scam, do these things in this order: call the National Cyber Crime Helpline on 1930 right away, tell your bank in writing, and file a complaint at cybercrime.gov.in. Under the RBI's customer-liability rules, reporting a third-party fraud to your bank within three working days of the bank's alert can leave you with zero liability. Speed matters more than anything else here.
- Call 1930 first, then tell your bank. Do both on the same day if you can.
- Report to the bank within 3 working days of its alert for zero liability on third-party fraud (RBI circular, 6 July 2017).
- Once you report, the bank must credit the amount back within 10 working days while it investigates.
- Keep screenshots, the transaction ID (UTR) and the scammer's number or UPI ID.
This guide covers money lost through a fraudulent UPI transaction. If the payment simply failed and the money is stuck, read our guide on UPI payments that failed but were debited instead. Information is current as of November 2026.
The five steps, in order
Most people lose time deciding who to call. This is the order that makes sense, because each step protects the next one.
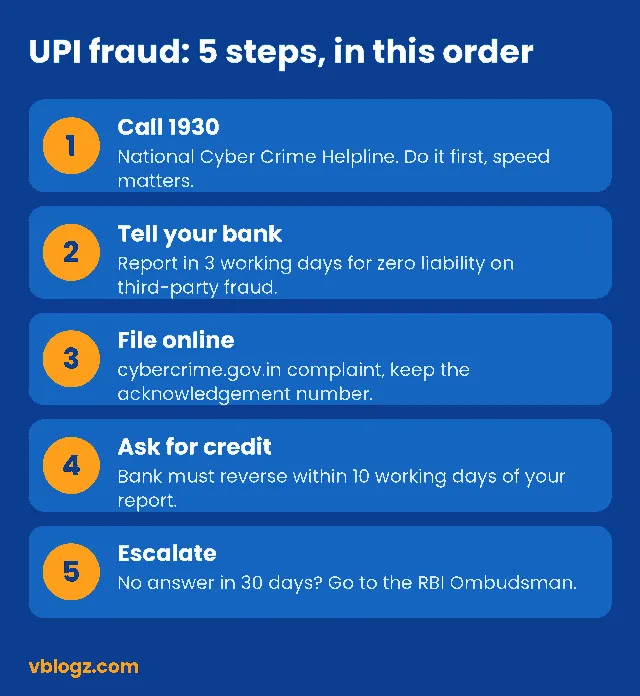
- Call 1930. This is India's national cybercrime helpline for financial fraud. Give the date, time, amount, your bank, the transaction ID and the scammer's phone number or UPI ID. The sooner the report reaches the system, the better the chance the receiving account can be flagged before the money is moved on.
- Contact your bank. Use the bank's 24x7 fraud line, its app or its website complaint link, and ask for a complaint number. Ask the bank to block your UPI access and card if you think your phone or credentials are compromised.
- File online at cybercrime.gov.in. Upload your screenshots and keep the acknowledgement number. Banks and police both ask for it.
- Ask the bank for credit. Write to the bank, quote your complaint number, and ask for the amount to be credited back under the RBI liability framework (explained below).
- Escalate if nothing happens. Use the UPI complaint route on the NPCI help portal and, if your bank hasn't replied satisfactorily after 30 days, the RBI's complaint portal at cms.rbi.org.in.
What the RBI rules say about getting your money back
The key document is the RBI circular "Customer Protection – Limiting Liability of Customers in Unauthorised Electronic Banking Transactions" (RBI/2017-18/15, dated 6 July 2017), which you can read on the RBI website. It applies to banks, small finance banks and payments banks. The SBI also explains the same time limits on its customer blog.
| When you report to the bank | Your liability |
|---|---|
| Fraud caused by the bank's own lapse, any time | Zero, whether or not you reported it |
| Third-party fraud, within 3 working days of the bank's alert | Zero |
| Third-party fraud, 4 to 7 working days | The transaction value or a capped amount, whichever is lower (₹5,000 for basic savings accounts, ₹10,000 for most other savings accounts, ₹25,000 for larger current accounts and credit cards above ₹5 lakh) |
| Beyond 7 working days | As set by your bank's Board-approved policy |
Two details people miss. First, working days are counted by your home branch's schedule and exclude the day you received the alert. Second, if the loss happened because you shared your PIN, OTP or password, you carry the loss until you report it. The bank carries any loss after you report.
Once you notify the bank, the circular says it should credit the disputed amount back (a "shadow reversal") within 10 working days and settle the complaint within 90 days at most. The burden of proving that you were at fault lies with the bank. One caution: this circular dates from 2017 and we could not confirm from the page whether the RBI has since consolidated it into newer directions, so check your own bank's current policy as well.
What to collect before you call
You'll be asked the same questions three times, so gather these once and keep them in a note on a second device.
- Transaction ID (UTR) and exact time, from the UPI app's history or the bank SMS.
- The scammer's phone number, UPI ID, name shown, and any chat, call log or link they sent.
- Screenshots of the payment, the app's collect request and any messages. Don't delete the chat.
- Your bank account details and the bank's alert message with its timestamp, since the 3-day clock starts there.
Common UPI scams to recognise
Knowing the pattern helps you report accurately and avoid a repeat. A "collect request" disguised as a refund is common: you only ever enter your PIN to send money, never to receive it. Fake customer-care numbers found through search results are another, as are QR codes sent by a "buyer" who says scanning will credit you. For calls claiming a police or customs case against you, see our guide to the digital arrest scam, and for fake discount sites, read about online shopping fraud in India.
Problems and limits to expect
- A refund isn't guaranteed. If you gave your OTP or PIN to the scammer, the bank may treat it as your negligence. Report anyway and ask for the investigation outcome in writing.
- The bank won't give a complaint number. Email the grievance address on its website and keep the sent copy. That timestamp supports your 3-day claim.
- Money already moved out of the scammer's account. Freezing works best when it's fast, which is why 1930 comes first. We can't promise a recovery rate, and none is published by the sources we checked.
- Protect your accounts afterwards. Change your UPI PIN and banking passwords, and consider passkeys for your Google account so one stolen password can't open your email too.
Frequently asked questions
How do I file a UPI fraud complaint online?
Register the complaint at cybercrime.gov.in with your transaction details and screenshots, and note the acknowledgement number. Then lodge a complaint with your bank and, if needed, on the NPCI help portal.
What is the UPI fraud complaint number?
The national cybercrime helpline for financial fraud is 1930. Your bank's own fraud helpline is printed on its website and on the back of your card.
How long does a UPI fraud refund take?
Under the RBI circular, the bank should credit the amount within 10 working days of your report and resolve the complaint within 90 days. In practice, timing depends on how the fraud happened and on your bank's investigation.
Can I report UPI fraud after several days?
Yes, but the later you report, the less protection you have. Past 7 working days, your liability follows your bank's Board-approved policy.
This is general information, not legal advice. For a large loss, also visit your local cyber police station.

Comments 0
No comments yet. Start the conversation.